
Financial literacy programme conducted in Seyochung to train SHGs and families in money management.
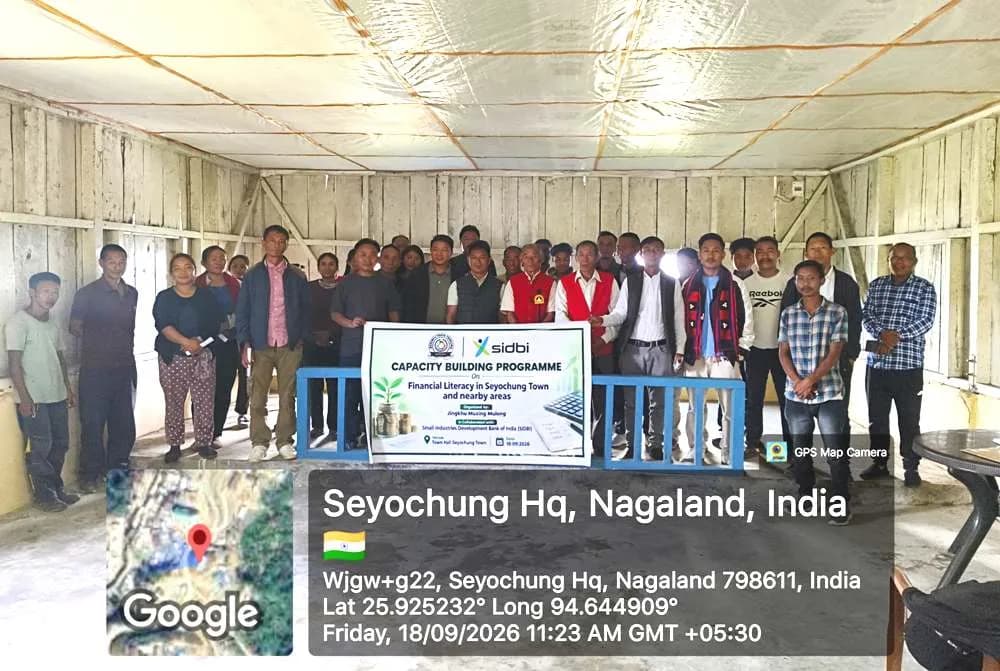
KIPHIRE — A capacity-building programme on financial literacy was conducted at the Town Hall in Seyochung town under Kiphire district on September 18.
The programme was organised by Jingkhu Muzing Mulong in collaboration with the Small Industries Development Bank of India. It focused on improving financial knowledge and assisting families, self-help groups, and livelihood entrepreneurs in making informed financial decisions.
The Chief Executive Officer of Akehda Amulung Kiphire conducted the session, covering key topics such as earning, spending, saving, borrowing, and financial protection. Participants were encouraged to prepare household budgets, track daily expenses, and build the habit of regular savings, highlighting that even small contributions help secure families financially.
Attention was also given to self-help group financial management. Participants were taught to maintain proper records of savings, loans, and repayments and to observe the Panchasutra principle comprising regular meetings, regular savings, internal lending, timely repayment, and up-to-date account books.
The session explained responsible borrowing, stressing the need to understand interest rates, fees, total repayment amounts, and repayment schedules prior to taking loans. The difference between flat interest rates and reducing-balance interest rates was also explained.
Read more local news: ‘Time Travel to Nagaland, 1979’ exhibition extended till September 25
On digital financial safety, participants were advised never to share one-time passwords, UPI PINs, ATM PINs, or account passwords, and to remain alert against suspicious links, fraudulent calls, QR code scams, fake rewards, and fraudulent loan offers.
The session further covered insurance, government financial inclusion schemes, banking services, and livelihood entrepreneurship. Participants were advised to keep household and business finances separate, maintain business records, and track costs and profits.
The programme concluded with a seven-day financial action plan, urging participants to record income, track expenses, save regularly, check bank and group records, learn fraud prevention methods, and define financial goals.
Longtili Sangtam
Our correspondent