
When interest rates increase, your EMI or loan tenure can change, and for floating-rate loans, a rate increase can raise your monthly repayment or extend the repayment period.
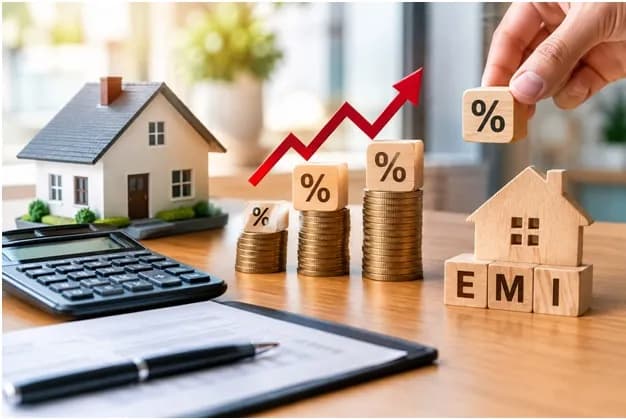
When interest rates increase, your EMI or loan tenure can change, depending on your lender's policy and loan terms. For floating-rate loans, a rate increase can raise your monthly repayment or extend the repayment period.
A mortgage loan EMI calculator can help you understand the potential impact of a rate change and plan your finances accordingly.
● A rise in interest rates can increase your EMI or extend your loan tenure.
● Keeping the EMI unchanged can result in a longer tenure and higher total interest outgo.
● Increasing the EMI can help maintain the existing tenure but raises your monthly repayment.
● Your lender's policy and loan terms determine how the rate change affects your repayment.
● A mortgage loan EMI calculator can help you compare different repayment scenarios.
● Part-prepayment can reduce your outstanding principal and help manage the impact of higher interest costs.
Floating-rate mortgage loans are linked to a benchmark or reference rate, depending on the lender and loan product. When the applicable benchmark or reference rate changes, the interest rate on your loan may also change.
The frequency and extent of the change depend on your loan agreement and the lender's rate-reset mechanism. Therefore, check your loan documents to understand how changes in interest rates can affect your repayment.
When your applicable interest rate increases, your lender can adjust your repayment in different ways based on the loan terms.
If your remaining tenure stays unchanged, a higher interest rate can increase your EMI. This means a higher monthly repayment while keeping the original repayment period.
Some repayment structures keep the EMI unchanged and extend the remaining tenure when the interest rate increases. This reduces the immediate impact on your monthly budget but can increase the total interest paid over the loan period.
The impact depends on:
● Your lender's policy
● Loan type and terms
● Remaining principal
● Remaining tenure
● Applicable interest rate
● Rate-reset mechanism
Check your loan agreement or lender communication to understand which adjustment applies to your loan.
A higher mortgage loan interest rate does not necessarily mean you have to accept a significantly higher overall repayment. You can consider the following options:
● Make a part-prepayment: Using surplus funds to reduce the outstanding principal can lower the interest payable over the remaining tenure.
● Review your EMI and tenure: Compare the impact of increasing your EMI with extending the tenure.
● Check your interest rate options: If your lender offers different rate structures, compare the applicable terms and charges before making a switch.
● Track your loan regularly: Review your loan statement and lender communication whenever the applicable interest rate changes.
Feature | Details |
Loan amount | Up to Rs. 15.50 crore* |
Interest rate | 7.5% to 14.25% p.a.* |
Repayment tenure | Up to 15 years* |
Disbursal | Within 72 hours* of approval, subject to verification |
How can you apply for Bajaj Finance Loan Against Property?
You can start the Bajaj Finance Loan Against Property application online.
The application journey generally involves:
1. Visit the Bajaj Finance Loan Against Property page.
2. Select the option to check your loan offer.
3. Enter your mobile number and verify it using the One-Time Password (OTP).
4. Provide your personal details.
5. Provide the property details.
6. Check your eligibility and available offer.
7. Review the loan details before proceeding.
The application may require additional documentation and verification before approval and disbursal.
*Terms and conditions apply.
No. Depending on your lender's policy and loan terms, the lender may increase your EMI, extend the loan tenure or make another applicable adjustment. Check your loan agreement to understand how rate changes are handled.
The frequency depends on the benchmark and rate-reset terms applicable to your loan. Check your loan agreement or lender communication for the applicable reset frequency.
Some lenders may offer a fixed-rate option or a conversion facility, subject to applicable terms and charges. Check with your lender before making a decision.
Yes. If you take a floating-rate loan after an interest rate increase, the applicable rate and resulting EMI will be based on the terms offered when you take the loan.
You can consider increasing your EMI, making a part-prepayment or reviewing your repayment tenure. Use a mortgage loan EMI calculator to compare the impact of different repayment options before making a decision.
A rise in mortgage interest rates can increase your EMI, extend your loan tenure or affect your total interest outgo. Understanding how your lender adjusts repayments can help you prepare for changes in your monthly obligations.
Use a mortgage loan EMI calculator to compare repayment scenarios and assess the impact of a potential rate increase before making financial decisions.
*Terms and conditions apply.